Louisiana Flood and Home Insurance Guide for Buyers: St. Tammany, Jefferson and Orleans
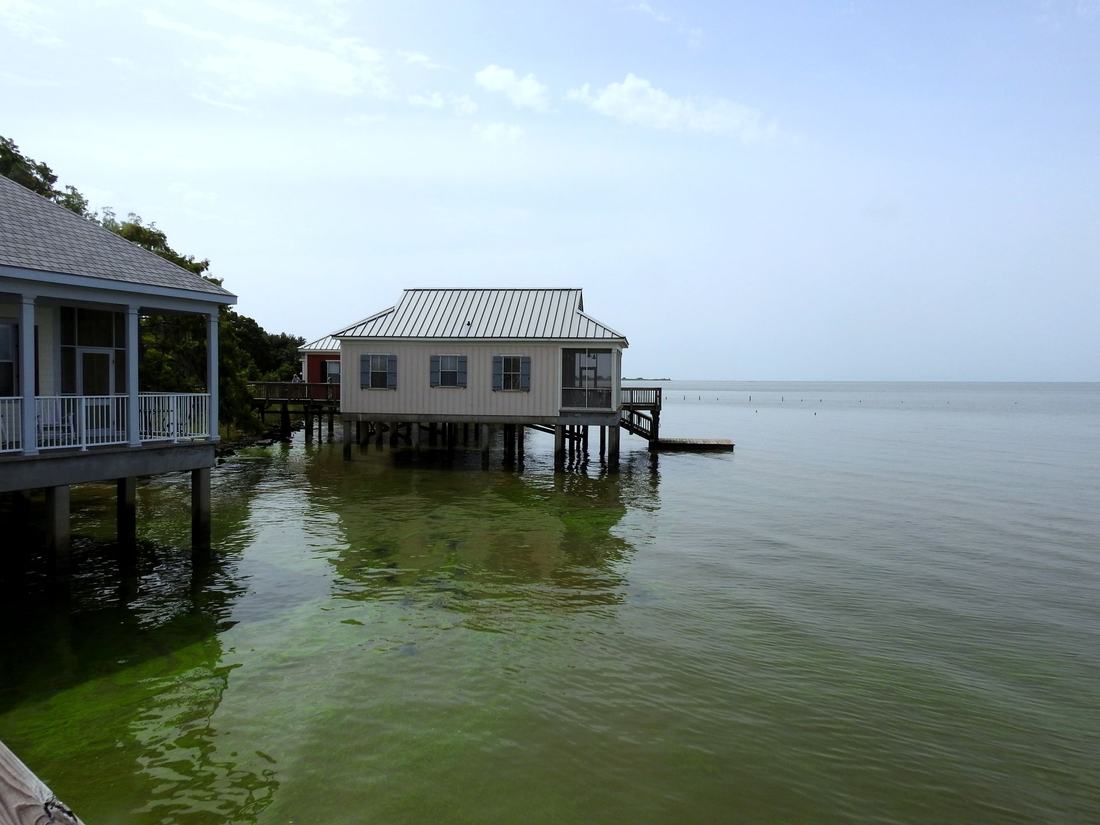
Photo: Mark Holloway. CC BY 2.0. Source: Wikimedia Commons.
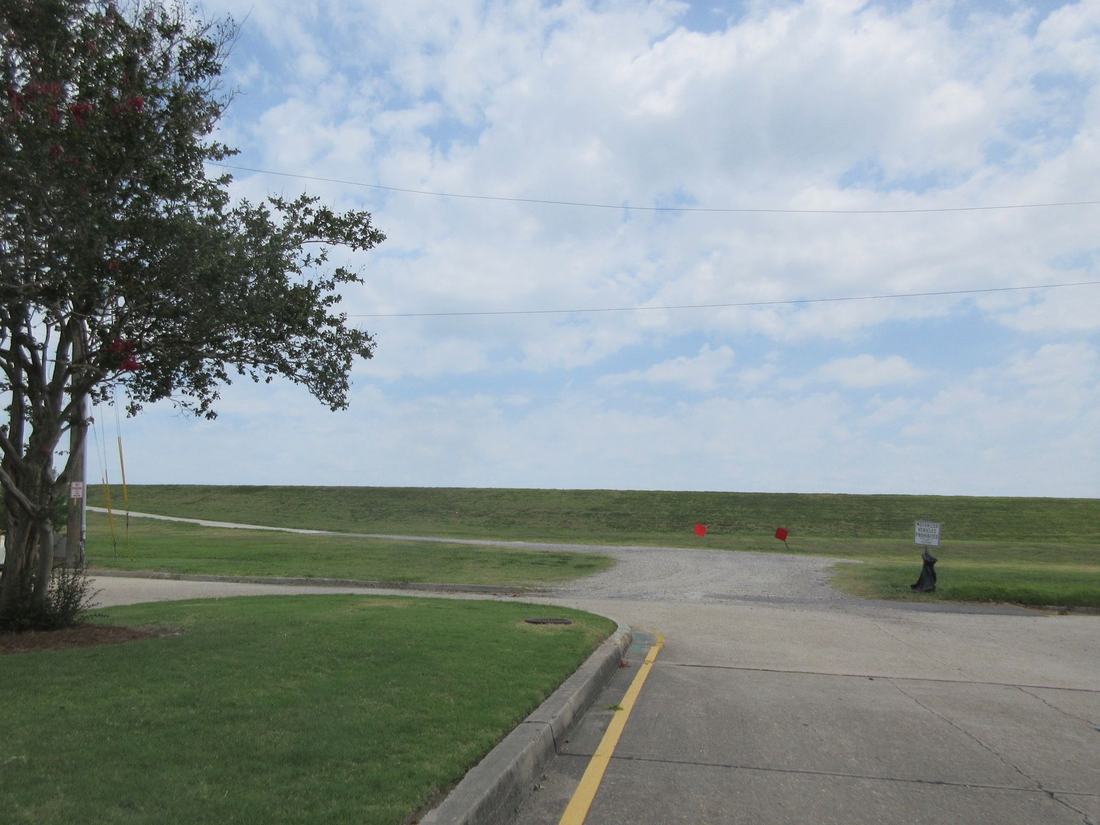
Photo: Infrogmation of New Orleans. CC BY-SA 4.0. Source: Wikimedia Commons.
In southeast Louisiana, the cost of insurance can change what a home really costs each month as much as the interest rate does. Cynthia "Cyndi" Benbow, DVM, a licensed real estate agent and REALTOR® with eXp Realty, LLC helps buyers get the flood and wind answers on a specific address early, while there is still time to negotiate or walk away. Cyndi is not an insurance agent. This guide explains the process and the documents. A licensed agent quotes the policy.
The Short Version
- Look up the flood zone for the exact address.
- Ask the seller for an elevation certificate and any existing flood policy.
- Get flood, wind and homeowners quotes on that address during your inspection period, not after.
- Ask about the hurricane deductible, not just the premium.
- Ask whether the roof has a FORTIFIED certificate, or what it would take to get one.
Step 1: Find the Flood Zone
Look up the address on FEMA's Flood Map Service Center. The map shows the flood zone and the base flood elevation where one has been set. Flood risk is set parcel by parcel, so a neighbor's zone or quote does not answer the question for your house.
Each parish also has its own map tools:
- St. Tammany Parish: St. Tammany Planning & Development can answer floodplain and elevation questions for unincorporated addresses. Towns and cities have their own offices.
- Jefferson Parish: the JeffMap viewer shows parcel information.
- Orleans Parish: the City of New Orleans address lookup on nola.gov shows zoning and district information for an address.
A low-risk zone on the map does not mean a home cannot flood. Many flood claims come from outside the high-risk zones, and some areas sit behind levees that lower, but do not remove, the risk.
Step 2: Get the Elevation Certificate
An elevation certificate is a FEMA form completed by a licensed surveyor or engineer. It records the height of the lowest floor and other features compared with the base flood elevation. Ask the seller if one exists. If not, you can order one during the inspection period. It can affect both the price of flood insurance and what you can do if you renovate.
Step 3: Flood Insurance, NFIP or Private
- NFIP: the National Flood Insurance Program, run by FEMA and sold through insurance agents. FEMA's current pricing method, which began in October 2021, rates each building on its own features rather than on the flood zone alone. Learn the basics at FloodSmart.
- Private flood: some private insurers write flood policies. Compare coverage, not just price.
- Waiting period: a new NFIP policy usually takes 30 days to take effect, with exceptions, including when the policy is required for a new loan at closing. Do not wait until the week of closing.
- Assuming a policy: an existing NFIP policy can sometimes be transferred to a buyer. Ask the seller and your agent.
- Lenders: if a home is in a high-risk zone and the loan is federally backed or regulated, flood insurance is usually required.
Step 4: Wind, Hurricane Deductibles and Homeowners Coverage
Homeowners policies in Louisiana often carry a separate hurricane or named-storm deductible, frequently set as a percentage of the dwelling coverage rather than a flat dollar amount. Ask every quote for that deductible in dollars. Some policies exclude wind and require a separate wind policy. If private insurers will not write a home, Louisiana Citizens Property Insurance Corporation is the state's insurer of last resort. Check a company or agent's license with the Louisiana Department of Insurance.
Step 5: FORTIFIED Roofs
FORTIFIED is a construction standard from IBHS, a research institute funded by the insurance industry. Louisiana law requires insurers to offer a discount or credit for homes built or retrofitted to it. The Louisiana Department of Insurance's Fortify Homes Program has offered grants of up to $10,000 toward a FORTIFIED Roof on eligible homestead properties when funding is open. Ask the seller for the FORTIFIED certificate if the roof has one, and ask your agent what discount it earns.
What Differs by Parish
| St. Tammany | Jefferson | Orleans | |
|---|---|---|---|
| Who handles permits and floodplain questions | The parish for unincorporated areas; each town or city inside its limits | The parish for unincorporated areas such as Metairie; cities such as Kenner have their own | The City of New Orleans |
| Common home types | Slab homes, raised homes near the lake and rivers, rural homes on wells and septic | Slab ranches, raised rebuilds, older homes near Metairie Road | Raised historic homes on piers, slab homes, condos |
| Watch for | Rivers, bayous and lakefront lots in different zones from high ground nearby | Below-sea-level drainage and street flooding in heavy rain | Below-sea-level drainage, historic-district rules for elevating a home |
Neighborhood guides with address-level checks: Eden Isles · Lakeview · Old Metairie · Tchefuncte River homes
Questions to Ask the Seller
- Has the home ever flooded or had a flood or wind claim? Louisiana's property disclosure form asks about known flooding.
- Is there an elevation certificate, a current flood policy and a FORTIFIED certificate?
- When was the roof replaced, and is there a wind-mitigation or roof inspection report?
- Has the home been raised, and were permits and final inspections completed?
How Cyndi Helps
Cyndi puts the insurance step on the calendar from day one of a contract. She gathers the elevation certificate, flood zone and roof documents, shares them with your insurance agent, and builds the inspection period around getting quotes back in time.
BenbowIQ™ Market Tools for Southeast Louisiana
Cyndi's BenbowIQ™ tools use public market data and name their sources and dates. They show area trends. They do not value any one home.
- Market Pulse: choose Covington, Madisonville, Mandeville, Metairie, New Orleans or Slidell, or type a ZIP code, to compare an area with its parish, Louisiana and the U.S.
- Price Map: see ZIP-level trends across St. Tammany, Orleans and Jefferson parishes.
- Rate Tracker: the 30-year mortgage rate next to home values over time. Turn on the Louisiana hurricane markers to see storm dates on the same chart.
- Home Value: ask Cyndi for a comparative market analysis of a home.
- Market Watch: a short monthly email update for a city, parish or ZIP code. Unsubscribe any time.
More: Eden Isles · Lakeview · Northshore vs. New Orleans · Buyer resources
Flood and Insurance Questions
How do I find the flood zone for a Louisiana home?
Look up the exact address on FEMA's Flood Map Service Center, then ask the seller for an elevation certificate. Flood risk is set parcel by parcel, so a neighbor's zone or quote does not answer the question for your house.
When should I get insurance quotes when buying a home in Louisiana?
During your inspection period, before you are committed. Ask for flood, wind and homeowners quotes on the exact address, and ask for the hurricane deductible in dollars.
How long does a new flood insurance policy take to start?
A new NFIP policy usually takes 30 days to take effect, with exceptions, including when flood insurance is required for a new loan at closing. Ask your insurance agent early.
What is a FORTIFIED roof in Louisiana?
A roof built or retrofitted to the FORTIFIED standard set by IBHS, a research institute funded by the insurance industry. Louisiana law requires insurers to offer a discount or credit for it, and the state's Fortify Homes Program has offered grants toward one when funding is open.
Is Cyndi an insurance agent?
No. Cyndi is a REALTOR® who helps you gather the flood zone, elevation certificate and roof documents and schedule quotes in time. A licensed insurance agent quotes the policy.
Talk With Cyndi About Flood and Insurance
Call or text Cyndi at 504.301.5850 to set up a private consultation, or request a comparative market analysis.
Private Tours by Request: Private, blacked-out SUVs with professional drivers and a dedicated concierge are available for private home and property tours and area orientations, by request only. All arrangements are confirmed with you in advance, and every driver and concierge team member is available to sign a non-disclosure agreement.
Photo credits
Photos on this page are used under the licenses below. CC BY and CC BY-SA works require this credit. Share-alike licenses also require that adapted copies of those photos stay under the same license.
- Hero photo (Park buildings on piers over Lake Pontchartrain at Fontainebleau State Park, Mandeville, Louisiana): Mark Holloway. CC BY 2.0. File page on Wikimedia Commons.
- Supporting photo (The grassed Lake Pontchartrain levee at the north end of Severn Avenue, Metairie, Louisiana): Infrogmation of New Orleans. CC BY-SA 4.0. File page on Wikimedia Commons.


Official area information: FEMA Flood Map Service Center.